
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Vega bucket؟

Definition 26.7 Derivatives and Volatility · الفصل 26 — Options Market Making in Practice

A vega bucket is a range of expiries (and, in finer schemes, of moneyness) over which a book’s vega is summed and limited; a book’s vega profile is its vega by bucket, and limits apply to each bucket separately.
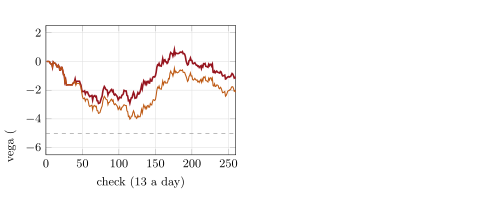
Vega by bucket of a toy options market maker facing a month of put demand, with quotes shaded as each bucket approaches its limit (dashed) and without. Data: the tutorial.
Figure 26.4. Vega by bucket of a toy options market maker facing a month of put demand, with quotes shaded as each bucket approaches its limit (dashed) and without. Data: the tutorial.

أمثلة

Example 26.8 (A month of put demand)

A toy market maker quotes 15 series (one, three and six months; strikes 90 to 110) for 20 days, 13 checks a day. Orders of 10 contracts arrive three times a check; uninformed customers buy puts two times in three and calls half the time; one order in five is informed. The theo errs by 0.5 point, the half-width is 0.4 point, and the delta is hedged at every check at 5 basis points. Limits are $3 000, $5 000 and $6 000 of vega per point. With shading, the book’s six-month vega peaks at −$3 369-\$3\,369 and the P&L is $11 141: edge $36 280, selection −$8 720-\$8\,720, hedging −$9 815-\$9\,815, inventory −$6 605-\$6\,605. Without it, the same flow drives the six-month vega to −$5 033-\$5\,033, the inventory loses $15 240, and the month ends at −$607-\$607 (Figure 26.4). One path proves nothing about averages. It shows where the risk goes when nothing leans against the flow.

اقرأ في الفصل →