 Coach
A vega bucket is a range of expiries (and, in finer schemes, of moneyness) over which a book’s vega is summed and limited; a book’s vega profile is its vega by bucket, and limits apply to each bucket separately.
Exemplos
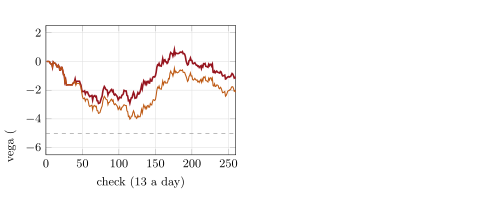
Example 26.8 (A month of put demand)
A toy market maker quotes 15 series (one, three and six months; strikes 90 to 110) for 20 days, 13 checks a day. Orders of 10 contracts arrive three times a check; uninformed customers buy puts two times in three and calls half the time; one order in five is informed. The theo errs by 0.5 point, the half-width is 0.4 point, and the delta is hedged at every check at 5 basis points. Limits are $3 000, $5 000 and $6 000 of vega per point. With shading, the book’s six-month vega peaks at and the P&L is $11 141: edge $36 280, selection , hedging , inventory . Without it, the same flow drives the six-month vega to , the inventory loses $15 240, and the month ends at (Figure 26.4). One path proves nothing about averages. It shows where the risk goes when nothing leans against the flow.