Todos los libros

Profesional

Apps Acerca de Coach Iniciar sesión Empezar a leer

Quantitative Finance · Glosario

¿Qué es VIX option?

Definition 14.11 Derivatives and Volatility · Capítulo 14 — Variance Swaps and Volatility Derivatives

A VIX option is a European option on the volatility index at its expiry. It is cash-settled, and its natural underlying is the VIX future of the same expiry, so it is quoted with Black’s formula on the future.
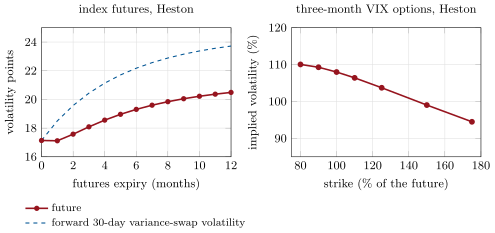

The volatility index under the calibrated Heston model. Left: futures lie below the forward variance-swap volatility by a convexity gap that grows with expiry. Right: the three-month smile of options on the index slopes down, the opposite of the market’s upward slope. Data: the tutorial.
Figure 14.3. The volatility index under the calibrated Heston model. Left: futures lie below the forward variance-swap volatility by a convexity gap that grows with expiry. Right: the three-month smile of options on the index slopes down, the opposite of the market’s upward slope. Data: the tutorial.
Leer en el capítulo →