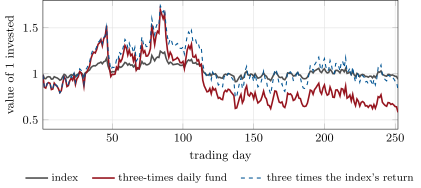
Volatility decay is the shortfall of a leveraged fund’s multi-day return relative to times (or the -th power of) the index’s return over the same period, caused by daily resetting in a volatile market.
 Coach
Connexion
Commencer la lecture
Quantitative Finance · Glossaire
Volatility decay is the shortfall of a leveraged fund’s multi-day return relative to times (or the -th power of) the index’s return over the same period, caused by daily resetting in a volatile market.