جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى XVA charge؟

Definition 20.9 Rates, Credit, XVA and Risk · الفصل 20 — The Valuation-Adjustment Desk

The XVA charge is the amount the XVA desk takes from the originating desk when a trade is booked: the trade’s incremental adjustments, paid upfront or converted into a running spread on the trade, charge=XVA/(N⋅A)\text{charge} = \mathrm{XVA}/(N\cdot A) with AA the trade’s annuity.

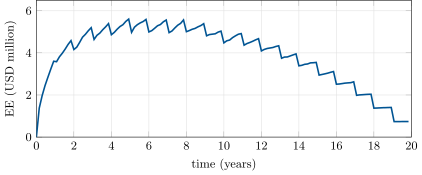
Expected exposure of the twenty-year swap on which the bank receives fixed from the unrated client: it peaks after about five years and runs off over the remaining fifteen. Data: the chapter’s tutorial.
Figure 20.4. Expected exposure of the twenty-year swap on which the bank receives fixed from the unrated client: it peaks after about five years and runs off over the remaining fifteen. Data: the chapter’s tutorial.

أمثلة

Example 20.10 (The twenty-year quote)

The client receives floating and pays the par rate of 4.11% on USD 100 million for twenty years; no CSA. On 4 000 paths the bank’s expected exposure peaks at USD 5.65 million after five years (Figure 20.4). With the proxy curve, the CVA is USD 1 649 494; funding at 80 basis points costs 343 872; with capital charged at a 10% hurdle (SA-CCR at a 100% risk weight, and CVA capital at the 7% risk weight for unrated industrials), the KVA is 3 141 826. Over the swap’s annuity of 13.67, that is 12.1, 2.5 and 23.0 basis points a year: 37.6 in all.

اقرأ في الفصل →