 Coach
The XVA charge is the amount the XVA desk takes from the originating desk when a trade is booked: the trade’s incremental adjustments, paid upfront or converted into a running spread on the trade, with the trade’s annuity.
Exemples
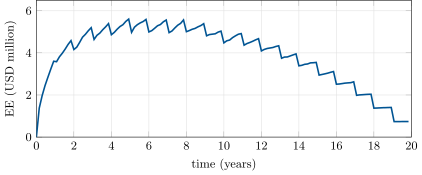
Example 20.10 (The twenty-year quote)
The client receives floating and pays the par rate of 4.11% on USD 100 million for twenty years; no CSA. On 4 000 paths the bank’s expected exposure peaks at USD 5.65 million after five years (Figure 20.4). With the proxy curve, the CVA is USD 1 649 494; funding at 80 basis points costs 343 872; with capital charged at a 10% hurdle (SA-CCR at a 100% risk weight, and CVA capital at the 7% risk weight for unrated industrials), the KVA is 3 141 826. Over the swap’s annuity of 13.67, that is 12.1, 2.5 and 23.0 basis points a year: 37.6 in all.