Semua buku

Profesional

Aplikasi Tentang Pelatih Masuk Mulai membaca

Quantitative Finance · Glosarium

Apa itu Aggregational Gaussianity?

Definition 5.2 Research Craft: Predictors, Backtests, Measurement, Portfolios · Bab 5 — Stylised Facts of Returns

Aggregational Gaussianity is the tendency of returns summed over longer horizons to look more normal: their kurtosis falls towards three as the horizon grows, so that the shape of the distribution depends on the horizon.
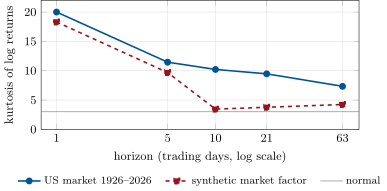
Kurtosis of log returns summed over non-overlapping horizons. The US market’s falls from 20.0 at one day to 9.5 at a month and 7.3 at a quarter; the book’s synthetic market factor (ten years, GJR-GARCH with Student-t shocks) falls from 18.3 to 3.8 at a month. Data: Kenneth R. French data library (derived statistics); firm.synthmkt, seed 1.
Figure 5.2. Kurtosis of log returns summed over non-overlapping horizons. The US market’s falls from 20.0 at one day to 9.5 at a month and 7.3 at a quarter; the book’s synthetic market factor (ten years, GJR-GARCH with Student-tt shocks) falls from 18.3 to 3.8 at a month. Data: Kenneth R. French data library (derived statistics); firm.synthmkt, seed 1.
Baca dalam konteks →
