جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Aim portfolio, multi-period optimisation؟

يُعرف أيضًا باسم: multi-period optimisation · aim portfolio

Definition 26.6 Research Craft: Predictors, Backtests, Measurement, Portfolios · الفصل 26 — Portfolio Construction II

Multi-period optimisation chooses trades by planning a sequence of future books under forecasts of returns, risks and costs, and executes the first (Boyd and co-authors). With quadratic costs λ2Δx⊤ΣΔx\frac\lambda2\Delta x^\top\Sigma\Delta x and signals whose predictive power decays at rates ϕk\phi_k, Gârleanu and Pedersen show that the optimal book trades each period a fraction a/λa/\lambda of the way from the current book to the aim portfolio (γΣ)−1∑kBkfk/(1+ϕka/γ)(\gamma\Sigma)^{-1}\sum_k B_k f_k/(1 + \phi_k a/\gamma), which weights slow signals more than fast ones, with aa the positive root of a2(1−ρ)+a(γ(1−ρ)+λρ)−γλ(1−ρ)=0a^2(1-\rho) + a(\gamma(1-\rho) + \lambda\rho) - \gamma\lambda(1-\rho) = 0 and ρ\rho the discount rate.

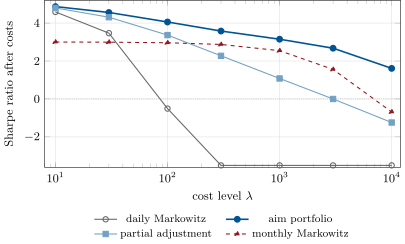
Sharpe ratio after quadratic costs against the cost level, for four trading rules on the three planted signals; values below -3.5 are drawn at -3.5. Data: rs_allocation.multiperiod.
Figure 26.2. Sharpe ratio after quadratic costs against the cost level, for four trading rules on the three planted signals; values below −3.5-3.5 are drawn at −3.5-3.5. Data: rs_allocation.multiperiod.
اقرأ في الفصل →