Tous les livres

Professionnel

Applis À propos Coach Connexion Commencer la lecture

Quantitative Finance · Glossaire

Qu'est-ce que « Average cost, realised and unrealised P&L » ?

Aussi appelé : average cost · realised P\&L · unrealised P\&L

Definition 7.6 Markets I: The Ecosystem and Exchange-Traded Markets · Chapitre 7 — P&L and the Accounting of a Position

Under the average cost convention an open position carries the quantity-weighted average price pˉ\bar p of the fills that built it. A fill that reduces the position by nn units at price pp realises ±n(p−pˉ)\pm n(p - \bar p) (plus for a long, minus for a short) and leaves pˉ\bar p unchanged; a fill that increases it updates pˉ\bar p; a fill that flips it closes the old position entirely and opens the remainder at pp. The realised P&L is the sum of these amounts; the unrealised P&L is q(m−pˉ)q(m - \bar p).

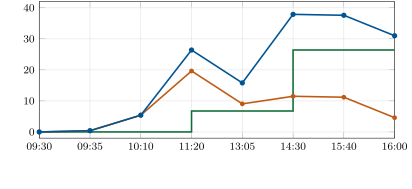
The day of , observed at each fill and at the close, marked at the mid. Realised P&L moves only when a sale reduces the position; the last point falls because the closing mid is below the afternoon’s prices while she is still long 30 000 shares. Data: the chapter’s fill list.
Figure 7.1. The day of Example 7.7, observed at each fill and at the close, marked at the mid. Realised P&L moves only when a sale reduces the position; the last point falls because the closing mid is below the afternoon’s prices while she is still long 30 000 shares. Data: the chapter’s fill list.

Exemples

Example 7.7 (Six fills)

The trader of the opening paragraph buys 20 000 at 49.30 and 20 000 at 49.55 (pˉ=49.425\bar p = 49.425), sells 10 000 at 50.10 (realising 10 000×0.675=6 75010\,000 \times 0.675 = 6\,750), buys 10 000 at 49.70 (pˉ=49.494\bar p = 49.494), sells 25 000 at 50.28 (realising 19 65619\,656), and buys 15 000 at 50.20 (pˉ=49.847\bar p = 49.847). She ends long 30 000 with $26 406 realised. Under first in, first out the same sales are matched to the oldest purchases and realise $28 750. Marked at 50.00 the unrealised parts are $4 594 and $2 250: both conventions total $31 000, as Proposition 7.5 says they must. The split matters for tax and for performance statistics (“win rate”); it never changes what the firm is worth.

Lire dans le chapitre →