Semua buku

Profesional

Aplikasi Tentang Pelatih Masuk Mulai membaca

Quantitative Finance · Glosarium

Apa itu Black model?

Definition 3.7 Derivatives and Volatility · Bab 3 — Black–Scholes Three Ways

The Black model assumes that the forward (or futures) price FtF_t of the underlying for delivery at TT is a driftless geometric Brownian motion under the TT-forward measure (One Quant Book 4, chapter 5): dFt=σFt dWtTdF_t=\sigma F_t\,dW^T_t. A European call with expiry TT is then worth

C=P(0,T)(FΦ(d1)−KΦ(d2)),d1,2=ln⁡(F/K)σT±12σT.C=P(0,T)\bigl(F\Phi(d_1)-K\Phi(d_2)\bigr),\qquad d_{1,2}=\frac{\ln(F/K)}{\sigma\sqrt T}\pm\tfrac12\sigma\sqrt T .
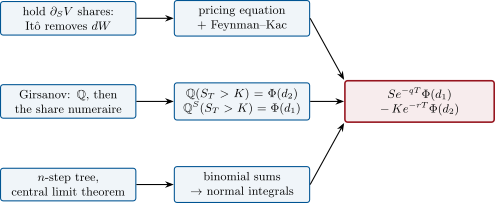
Three routes to one formula: replication (top), the martingale expectation (middle), the limit of the binomial tree (bottom). Each needs a different piece of mathematics and each generalises to a different numerical method.
Figure 3.3. Three routes to one formula: replication (top), the martingale expectation (middle), the limit of the binomial tree (bottom). Each needs a different piece of mathematics and each generalises to a different numerical method.
Baca dalam konteks →