جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Box spread؟

Definition 1.4 Derivatives and Volatility · الفصل 1 — No Arbitrage and the Fundamental Theorems

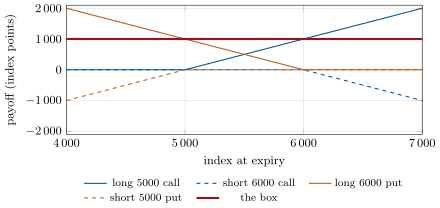
A box spread with strikes K1<K2K_1<K_2 and one expiry is a long call and a short put at K1K_1 together with a short call and a long put at K2K_2. At expiry it pays K2−K1K_2-K_1 in every state, so its price is P(0,T)(K2−K1)P(0,T)(K_2-K_1) and it is a zero-coupon bond.

The four legs of a 5 000–6 000 box spread at expiry. Each leg has its kink at its strike; the calls’ kinks and the puts’ kinks cancel, and the sum is the flat line at 1 000 points. Data: the chapter’s code.
Figure 1.1. The four legs of a 5 000–6 000 box spread at expiry. Each leg has its kink at its strike; the calls’ kinks and the puts’ kinks cancel, and the sum is the flat line at 1 000 points. Data: the chapter’s code.

أمثلة

Example 1.5 (Reading the rate off a box)

The one-year 5 000–6 000 box of the opening trades at 958.90 points. Its continuously compounded rate is −ln⁡(958.90/1000)=4.20%-\ln(958.90/1000)=4.20\%. A lender who buys it pays USD 95 890 and receives USD 100 000 in a year (the multiplier is USD 100 per point); a borrower sells it.

اقرأ في الفصل →