 Coach
A box spread with strikes and one expiry is a long call and a short put at together with a short call and a long put at . At expiry it pays in every state, so its price is and it is a zero-coupon bond.
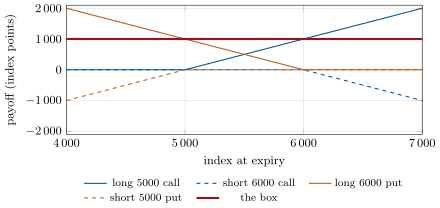
Voorbeelden
Example 1.5 (Reading the rate off a box)
The one-year 5 000–6 000 box of the opening trades at 958.90 points. Its continuously compounded rate is . A lender who buys it pays USD 95 890 and receives USD 100 000 in a year (the multiplier is USD 100 per point); a borrower sells it.