
Alle boeken

Professioneel

Apps Over Coach Inloggen Begin met lezen

Quantitative Finance · Begrippenlijst

Wat is Brennan–Schwartz algorithm?

Ook bekend als: Brennan--Schwartz algorithm

Definition 22.7 Derivatives and Volatility · Hoofdstuk 22 — Trees and Finite-Difference Pricers in Practice

The Brennan–Schwartz algorithm solves a tridiagonal system with the constraint V≥gV\ge g exactly when the exercise region is an interval at one end of the grid: it eliminates from the other end, then back-substitutes towards the exercise region, taking the maximum with gg at each node; its cost is that of one tridiagonal solve.
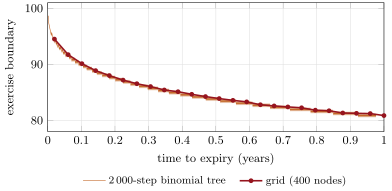
The American put’s exercise boundary (strike 100, 5%, 20%) by time to expiry: exercise below the curve. The tree’s boundary is a staircase of its nodes; the grid’s, refined between nodes, is smooth. Data: the tutorial.
Figure 22.3. The American put’s exercise boundary (strike 100, 5%, 20%) by time to expiry: exercise below the curve. The tree’s boundary is a staircase of its nodes; the grid’s, refined between nodes, is smooth. Data: the tutorial.
Lees in het hoofdstuk →