Todos os livros

Profissional

Apps Sobre Coach Entrar Começar a ler

Quantitative Finance · Glossário

O que é Brownian motion, Gaussian process?

Também chamado de: Gaussian process · Brownian motion

Definition 2.1 Quantitative Methods · Capítulo 2 — Brownian Motion

A Gaussian process is a process (Xt)(X_t) whose finite-dimensional laws (Xt1,…,Xtk)(X_{t_1}, \dots, X_{t_k}) are all multivariate normal; its law is fixed by its mean m(t)m(t) and covariance c(s,t)c(s,t). A (standard) Brownian motion (Wt)t≥0(W_t)_{t \ge 0} is an adapted process with W0=0W_0 = 0, continuous paths, and increments Wt−WsW_t - W_s independent of Fs\mathcal F_s and distributed N(0,t−s)\mathcal N(0, t - s) for s<ts < t.

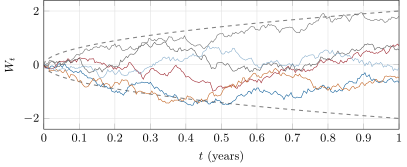
Six Brownian paths on [0,1] (250 steps) inside the envelope ± 2√ t (dashed), which holds 95% of the law at each fixed time. The spread grows like √ t, not like t. Data: the chapter’s tutorial, seeded.
Figure 2.1. Six Brownian paths on [0,1][0,1] (250 steps) inside the envelope ±2t\pm 2\sqrt t (dashed), which holds 95% of the law at each fixed time. The spread grows like t\sqrt t, not like tt. Data: the chapter’s tutorial, seeded.
Ler no capítulo →