
Tous les livres

Professionnel

Applis À propos Coach Connexion Commencer la lecture

Quantitative Finance · Glossaire

Qu'est-ce que « Calibration curve, isotonic regression » ?

Aussi appelé : calibration curve · isotonic regression

Definition 15.3 Research Craft: Predictors, Backtests, Measurement, Portfolios · Chapitre 15 — From Signal to Forecast

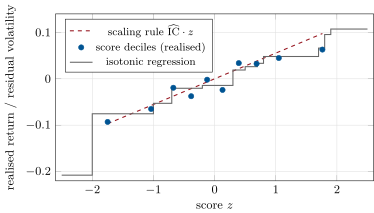
A calibration curve plots the mean realised return of names grouped by forecast (in bins) against the mean forecast. Isotonic regression fits the best non-decreasing function of the score to realised returns by least squares, by pooling adjacent groups that violate the order (Ayer, Brunk, Ewing, Reid and Silverman, 1955).
Calibration of the planted score on the last five years: mean realised return over residual volatility by score decile against the scaling rule with the IC estimated on the first five (0.055), and the isotonic fit. Data: rs_forecast on firm.synthmkt.
Figure 15.1. Calibration of the planted score on the last five years: mean realised return over residual volatility by score decile against the scaling rule with the IC estimated on the first five (0.055), and the isotonic fit. Data: rs_forecast on firm.synthmkt.
Lire dans le chapitre →