
Todos los libros

Profesional

Apps Acerca de Coach Iniciar sesión Empezar a leer

Quantitative Finance · Glosario

¿Qué es Call-spread overhedge?

Definition 15.3 Derivatives and Volatility · Capítulo 15 — Barriers and Digitals

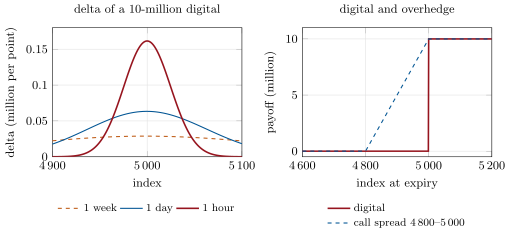
The call-spread overhedge prices and hedges a sold digital call as the call spread that dominates it: N/εN/\varepsilon calls struck at K−εK-\varepsilon less as many struck at KK. The spread pays at least the digital everywhere, and the difference in price, the overhedge, is charged to the buyer.
Left: the delta of a 10-million digital struck at 5 000 (20% volatility) as expiry approaches; one minute before the close it reaches 1.25 million per point, off this scale. Right: the digital’s payoff and the call spread that overhedges it; the extra payoff between 4 800 and 5 000 is what the overhedge charges for. Data: the chapter’s code.
Figure 15.1. Left: the delta of a 10-million digital struck at 5 000 (20% volatility) as expiry approaches; one minute before the close it reaches 1.25 million per point, off this scale. Right: the digital’s payoff and the call spread that overhedges it; the extra payoff between 4 800 and 5 000 is what the overhedge charges for. Data: the chapter’s code.
Leer en el capítulo →