جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى CMS spread option؟

Definition 6.11 Rates, Credit, XVA and Risk · الفصل 6 — Convexity Adjustments and Constant-Maturity Products

A CMS spread option pays max⁡(S1(T)−S2(T)−K,0)\max(S_1(T)-S_2(T)-K,0) at TpT_p on the difference of two CMS rates of different tenors observed at the same date, typically the ten-year and the two-year; a strip of them with K=0K=0 pays a steepener coupon.

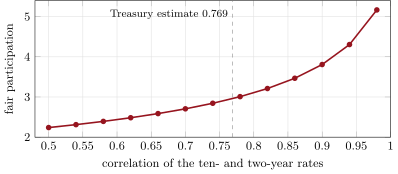
Fair participation of a ten-year steepener note (the weekend problem) as a function of the correlation between the ten- and two-year swap rates: the higher the correlation, the less volatile the spread and the cheaper each unit of its floor, so the more of it the note can pay. Data: the chapter’s tutorial.
Figure 6.4. Fair participation of a ten-year steepener note (the weekend problem) as a function of the correlation between the ten- and two-year swap rates: the higher the correlation, the less volatile the spread and the cheaper each unit of its floor, so the more of it the note can pay. Data: the chapter’s tutorial.

أمثلة

Example 6.12 (The spread’s volatility)

Over 2016–2026 daily changes of the two- and ten-year Treasury par yields had a correlation of 0.769 (chapter 3’s data, a proxy for swap rates). With the cube’s at-the-money volatilities for the one-year expiry, the spread of the ten- and two-year euro rates has a normal volatility of 45.1 basis points, well below either rate’s.

اقرأ في الفصل →