 Pelatih
A CMS spread option pays at on the difference of two CMS rates of different tenors observed at the same date, typically the ten-year and the two-year; a strip of them with pays a steepener coupon.
Contoh
Example 6.12 (The spread’s volatility)
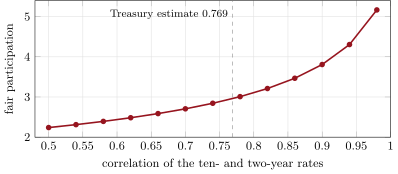
Over 2016–2026 daily changes of the two- and ten-year Treasury par yields had a correlation of 0.769 (chapter 3’s data, a proxy for swap rates). With the cube’s at-the-money volatilities for the one-year expiry, the spread of the ten- and two-year euro rates has a normal volatility of 45.1 basis points, well below either rate’s.