Todos los libros

Profesional

Apps Acerca de Coach Iniciar sesión Empezar a leer

Quantitative Finance · Glosario

¿Qué es Coherent risk measure?

Definition 21.12 Rates, Credit, XVA and Risk · Capítulo 21 — Market-Risk Measures

A risk measure ρ\rho is a coherent risk measure if it is monotone, translation invariant (ρ(L+c)=ρ(L)+c\rho(L+c) = \rho(L)+c), positively homogeneous (ρ(λL)=λρ(L)\rho(\lambda L) = \lambda\rho(L) for λ≥0\lambda\ge0) and subadditive (ρ(L1+L2)≤ρ(L1)+ρ(L2)\rho(L_1+L_2)\le\rho(L_1)+\rho(L_2)). Expected shortfall is coherent; VaR is not subadditive in general.
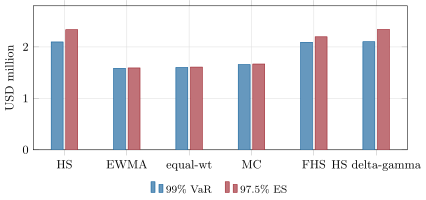
One-day 99% VaR and 97.5% ES of the book on 23 September 2026 by method. Normal methods agree with each other and give lower numbers; historical and filtered historical simulation see the fat tails, and their ES exceeds their VaR. Data: US Treasury par yields, ECB reference rates; the chapter’s tutorial.
Figure 21.1. One-day 99% VaR and 97.5% ES of the book on 23 September 2026 by method. Normal methods agree with each other and give lower numbers; historical and filtered historical simulation see the fat tails, and their ES exceeds their VaR. Data: US Treasury par yields, ECB reference rates; the chapter’s tutorial.
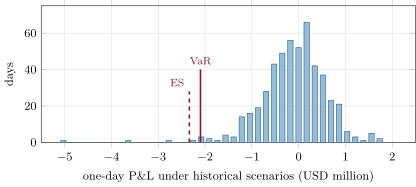
Distribution of the book’s P&L over the last 500 historical days applied to today’s positions, with the 99% VaR and the 97.5% ES. Data: US Treasury, ECB; the chapter’s tutorial.
Figure 21.2. Distribution of the book’s P&L over the last 500 historical days applied to today’s positions, with the 99% VaR and the 97.5% ES. Data: US Treasury, ECB; the chapter’s tutorial.

Ejemplos

Example 21.13 (Two concentrated bonds)

Each of two bonds defaults independently with probability 0.9%, losing 100. Each alone has a 99% VaR of zero; together, the probability of at least one default is 1.79%, so the 99% VaR is 100: diversifying raised VaR. Expected shortfall at 99% is 90 for each bond and 100.8 for the pair, less than their sum of 180.

Leer en el capítulo →