 Coach
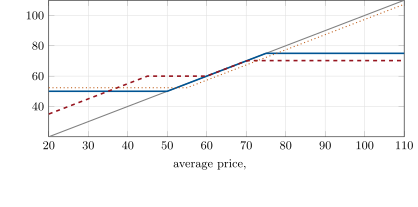
A producer’s collar buys a put and sells a call, usually with strikes chosen so that the premiums cancel (a zero-cost collar): its realised price is kept between the two strikes. A three-way collar adds a sold put below the bought one: the producer is protected only between the two put strikes, and the extra premium lets it raise the floor or the cap.
Exemples
Example 12.7 (What each structure costs)
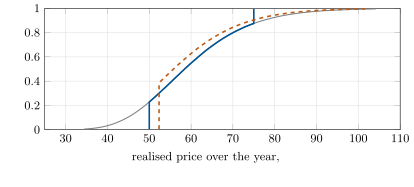
With the future at $60, 35% volatility and a year of monthly averaging, the 50/75 collar costs $0.07 a barrel, close to zero; the 55 average-price put costs $2.66. A three-way that buys the 60 put and sells the 45 put costs the same $2.66 if it also sells a call at $70.24. A producer with a budget of $50 a barrel would, unhedged, fall $8.43 short of it in the worst 5% of years; with either the collar or the put its worst-5% realised price stays above the budget.