
Todos os livros

Profissional

Apps Sobre Coach Entrar Começar a ler

Quantitative Finance · Glossário

O que é Collar, three-way collar?

Também chamado de: collar · three-way collar

Definition 12.6 Markets III: Commodities, Energy and Crypto · Capítulo 12 — Commodity Options and Structured Hedges

A producer’s collar buys a put and sells a call, usually with strikes chosen so that the premiums cancel (a zero-cost collar): its realised price is kept between the two strikes. A three-way collar adds a sold put below the bought one: the producer is protected only between the two put strikes, and the extra premium lets it raise the floor or the cap.
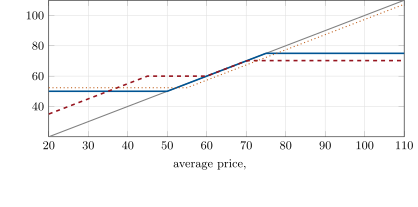
A producer’s realised price per barrel against the year’s average price. The collar keeps it between $50 and $75; the three-way protects from $60 down to $45 only, then follows the price down with a $15 cushion, and gives up everything above $70.24; the bought put keeps all the upside at the cost of its premium. Illustrative; data: the chapter’s tutorial.
Figure 12.3. A producer’s realised price per barrel against the year’s average price. The collar keeps it between $50 and $75; the three-way protects from $60 down to $45 only, then follows the price down with a $15 cushion, and gives up everything above $70.24; the bought put keeps all the upside at the cost of its premium. Illustrative; data: the chapter’s tutorial.
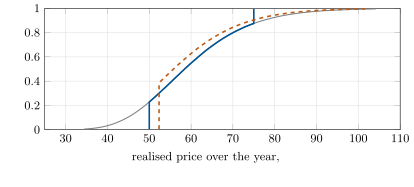
Distribution of a producer’s realised average price over a year, simulated from a $60 future with 35% volatility: unhedged, with the 50/75 collar, and with the 55 average-price put net of its $2.66 premium. The collar truncates both tails; the put truncates only the lower one, at a cost. Illustrative; data: the chapter’s tutorial.
Figure 12.4. Distribution of a producer’s realised average price over a year, simulated from a $60 future with 35% volatility: unhedged, with the 50/75 collar, and with the 55 average-price put net of its $2.66 premium. The collar truncates both tails; the put truncates only the lower one, at a cost. Illustrative; data: the chapter’s tutorial.

Exemplos

Example 12.7 (What each structure costs)

With the future at $60, 35% volatility and a year of monthly averaging, the 50/75 collar costs $0.07 a barrel, close to zero; the 55 average-price put costs $2.66. A three-way that buys the 60 put and sells the 45 put costs the same $2.66 if it also sells a call at $70.24. A producer with a budget of $50 a barrel would, unhedged, fall $8.43 short of it in the worst 5% of years; with either the collar or the put its worst-5% realised price stays above the budget.

Ler no capítulo →