 Coach
Over an interest period of calendar days with business days , fixings and weights , the calendar days from to the next business day, the rate compounded in arrears is
with for the dollar and euro and 365 for sterling. It is known only after the last fixing. Three conventions bring the payment date forward: a lookback of business days uses from days before each with the period’s own weights; an observation shift takes rates and weights from a period moved back by business days; a lockout freezes the last fixings at the one before them.
Exemples
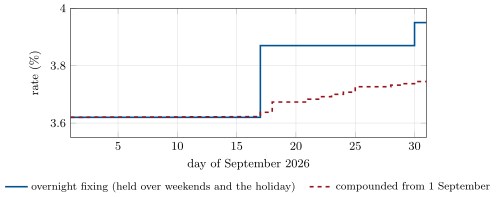
Example 1.16 (September 2026, illustrated)
Take illustrative fixings of 3.62% up to 16 September, 3.87% from the hike, and 3.95% on the quarter-end day, 30 September (Figure 1.3). Over 1 September to 1 October (30 days, 21 fixings, Labor Day on 7 September) the day-weighted average is 3.7393% and the compounded rate 3.7448%: compounding adds 0.54 basis points, against the 0.56 of Proposition 1.15 for a flat 3.74%. With a five-day lookback the rate is 3.6836%, 6.12 basis points lower, USD 5 098 on USD 100 million: the lookback moves five days of the new rate into the next period, where the borrower will pay them.