
All books

Professional

Apps About Coach Log in Start reading

Quantitative Finance · Glossary

What is Conformal prediction?

Definition 11.6 Machine Learning for Markets · Chapter 11 — Probabilistic Models and Uncertainty

Conformal prediction turns any forecast into prediction sets with a coverage guarantee: a score si=s(xi,yi)s_i = s(x_i, y_i) (for example ∣yi−y^i∣|y_i - \hat y_i|, or that divided by a predicted standard deviation) is computed on nn calibration examples, and the set for a new xx is {y:s(x,y)≤q^}\{y: s(x, y)\le\hat q\} with q^\hat q the ⌈(n+1)(1−α)⌉\lceil(n+1)(1 - \alpha)\rceil-th smallest calibration score (split conformal; Vovk, Gammerman and Shafer, 2005). The adaptive version updates the level online, αt+1=αt+γ(α−errt)\alpha_{t+1} = \alpha_t + \gamma(\alpha - \mathrm{err}_t), to keep the long-run error rate at α\alpha when the data drift (Gibbs and Candès, 2021).
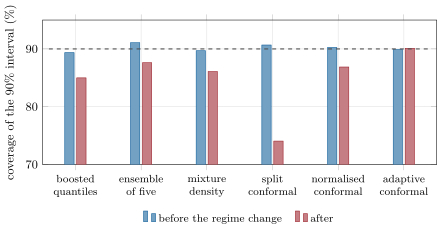
Coverage of 90% intervals on the test days, before and after the volatility regime (dashed: the nominal 90%). The three models’ own intervals, and conformal intervals around the boosted mean forecast: split conformal with raw errors, with errors normalised by the ensemble’s standard deviation, and adaptive. Data: ml_uncert.scores and ml_uncert.conformal.
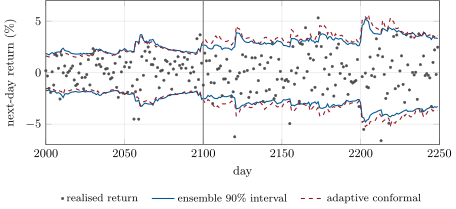
Figure 11.1. Coverage of 90% intervals on the test days, before and after the volatility regime (dashed: the nominal 90%). The three models’ own intervals, and conformal intervals around the boosted mean forecast: split conformal with raw errors, with errors normalised by the ensemble’s standard deviation, and adaptive. Data: ml_uncert.scores and ml_uncert.conformal.
One asset through the regime change at day 2 100 (vertical line): realised next-day returns, the ensemble’s 90% interval, and the adaptive conformal interval around the boosted mean. Both widen after the break; the conformal band widens further as its errors accumulate. Data: ml_uncert.conformal.
Figure 11.2. One asset through the regime change at day 2 100 (vertical line): realised next-day returns, the ensemble’s 90% interval, and the adaptive conformal interval around the boosted mean. Both widen after the break; the conformal band widens further as its errors accumulate. Data: ml_uncert.conformal.
Read in context →