
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Continuous futures series, back-adjustment, ratio adjustment؟

يُعرف أيضًا باسم: continuous futures series · back-adjustment · ratio adjustment

Definition 2.6 Research Craft: Predictors, Backtests, Measurement, Portfolios · الفصل 2 — Market Data for Research

A continuous futures series follows the contract a position would hold under a roll rule: the nearby contract until a roll date some days before its last trading day, then the next contract. Back-adjustment adds, to every price before a roll, the gap between the new and the old contract on the roll date, so that the series has no jump at the roll and its latest prices are real. Ratio adjustment multiplies every earlier price by the ratio of the new contract’s price to the old one’s on the roll date instead.
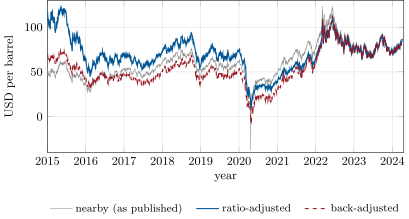
WTI crude oil futures, 2015 to April 2024: the nearby contract as published (with -37.63 on 20 April 2020), and continuous series rolling five trading days before each expiry, ratio-adjusted (starting at 118.33) and back-adjusted (starting at 70.23, negative in April 2020). All three end at the same price. Data: US Energy Information Administration, NYMEX settlements, contracts 1 and 2.
Figure 2.4. WTI crude oil futures, 2015 to April 2024: the nearby contract as published (with −37.63-37.63 on 20 April 2020), and continuous series rolling five trading days before each expiry, ratio-adjusted (starting at 118.33) and back-adjusted (starting at 70.23, negative in April 2020). All three end at the same price. Data: US Energy Information Administration, NYMEX settlements, contracts 1 and 2.
اقرأ في الفصل →