
Tous les livres

Professionnel

Applis À propos Coach Connexion Commencer la lecture

Quantitative Finance · Glossaire

Qu'est-ce que « Continuous futures series, back-adjustment, ratio adjustment » ?

Aussi appelé : continuous futures series · back-adjustment · ratio adjustment

Definition 2.6 Research Craft: Predictors, Backtests, Measurement, Portfolios · Chapitre 2 — Market Data for Research

A continuous futures series follows the contract a position would hold under a roll rule: the nearby contract until a roll date some days before its last trading day, then the next contract. Back-adjustment adds, to every price before a roll, the gap between the new and the old contract on the roll date, so that the series has no jump at the roll and its latest prices are real. Ratio adjustment multiplies every earlier price by the ratio of the new contract’s price to the old one’s on the roll date instead.
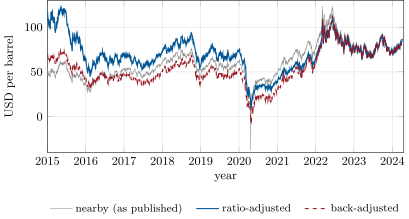
WTI crude oil futures, 2015 to April 2024: the nearby contract as published (with -37.63 on 20 April 2020), and continuous series rolling five trading days before each expiry, ratio-adjusted (starting at 118.33) and back-adjusted (starting at 70.23, negative in April 2020). All three end at the same price. Data: US Energy Information Administration, NYMEX settlements, contracts 1 and 2.
Figure 2.4. WTI crude oil futures, 2015 to April 2024: the nearby contract as published (with −37.63-37.63 on 20 April 2020), and continuous series rolling five trading days before each expiry, ratio-adjusted (starting at 118.33) and back-adjusted (starting at 70.23, negative in April 2020). All three end at the same price. Data: US Energy Information Administration, NYMEX settlements, contracts 1 and 2.
Lire dans le chapitre →