 Coach
The correlation risk premium is the difference between the average correlation implied by index and member option prices and the correlation then realised; it is positive on average because correlation rises in crashes, when diversification is most needed.
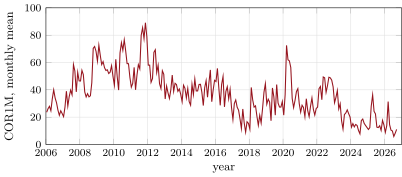
s2_fetch_cor.