
Alle boeken

Professioneel

Apps Over Coach Inloggen Begin met lezen

Quantitative Finance · Begrippenlijst

Wat is Correlation risk premium?

Definition 2.2 Strategies II: Volatility, Relative Value, Macro and the Bank Desks · Hoofdstuk 2 — Dispersion and Correlation

The correlation risk premium is the difference between the average correlation implied by index and member option prices and the correlation then realised; it is positive on average because correlation rises in crashes, when diversification is most needed.
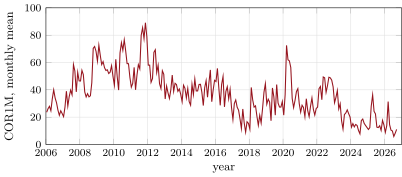
Cboe’s 1-Month Implied Correlation Index (the average correlation among the S&P 500’s 50 largest members implied by index and single-stock options), monthly means, January 2006 to September 2026. Derived from Cboe’s index history; the raw series is not redistributed. Data: s2_fetch_cor.
Figure 2.1. Cboe’s 1-Month Implied Correlation Index (the average correlation among the S&P 500’s 50 largest members implied by index and single-stock options), monthly means, January 2006 to September 2026. Derived from Cboe’s index history; the raw series is not redistributed. Data: s2_fetch_cor.
Lees in het hoofdstuk →