
सभी किताबें

पेशेवर

ऐप्स परिचय Coach लॉग इन पढ़ना शुरू करें

Quantitative Finance · शब्दावली

Correlation swap क्या है?

Definition 17.9 Derivatives and Volatility · अध्याय 17 — Multi-Asset Options

A correlation swap pays the weighted average of the pairwise correlations realised between the members of a basket, ∑i<jwiwjρ^ij/∑i<jwiwj\sum_{i<j}w_iw_j\hat\rho_{ij}/\sum_{i<j}w_iw_j, against a fixed strike. It isolates the correlation that a dispersion trade holds only approximately.
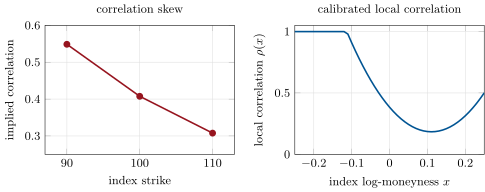
A synthetic index of twenty stocks with flat smiles, whose own smile is chapter 9’s. Left: the implied correlation at three strikes. Right: the local correlation, a function of the index level, that reproduces the index smile at the three strikes. It is capped at one below the money and falls as the index rises to about 10% above its start; the upturn beyond is an artefact of a quadratic fitted to three strikes, which constrain nothing there. Data: the tutorial.
Figure 17.2. A synthetic index of twenty stocks with flat smiles, whose own smile is chapter 9’s. Left: the implied correlation at three strikes. Right: the local correlation, a function of the index level, that reproduces the index smile at the three strikes. It is capped at one below the money and falls as the index rises to about 10% above its start; the upturn beyond is an artefact of a quadratic fitted to three strikes, which constrain nothing there. Data: the tutorial.
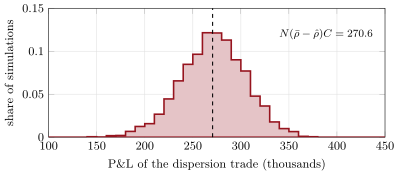
The P&L of a one-year dispersion trade (short index variance, vega notional 100 000, long member variance in the hedge amounts) over 4 000 simulated years in which correlation realises fifteen points below implied. The dashed line is the formula. Data: the tutorial.
Figure 17.3. The P&L of a one-year dispersion trade (short index variance, vega notional 100 000, long member variance in the hedge amounts) over 4 000 simulated years in which correlation realises fifteen points below implied. The dashed line is the formula. Data: the tutorial.

उदाहरण

Example 17.10 (Correlation fifteen points below implied)

Sell one-year index variance with a vega notional of 100 000 at the strip’s 22.12%, a variance notional of 2 261 per variance point, and buy the members’ variance in the hedge amounts. If each member realises its implied volatility and correlation realises 0.409, fifteen points below the implied 0.559, the P&L is 2 261×0.15×798=270 6002\,261\times0.15\times798=270\,600, with C=798C=798 variance points. Over 4 000 simulated years of daily returns the P&L averages 271 000, with a standard deviation of 34 000 from the noise in realised volatilities and correlation. Nine times in ten it lies between 215 000 and 326 000 (Figure 17.3).

अध्याय में पढ़ें →