 Pelatih
A correlation swap pays the weighted average of the pairwise correlations realised between the members of a basket, , against a fixed strike. It isolates the correlation that a dispersion trade holds only approximately.
Contoh
Example 17.10 (Correlation fifteen points below implied)
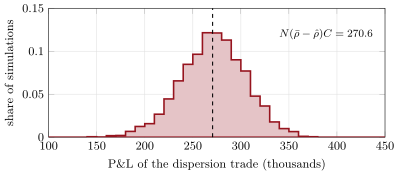
Sell one-year index variance with a vega notional of 100 000 at the strip’s 22.12%, a variance notional of 2 261 per variance point, and buy the members’ variance in the hedge amounts. If each member realises its implied volatility and correlation realises 0.409, fifteen points below the implied 0.559, the P&L is , with variance points. Over 4 000 simulated years of daily returns the P&L averages 271 000, with a standard deviation of 34 000 from the noise in realised volatilities and correlation. Nine times in ten it lies between 215 000 and 326 000 (Figure 17.3).