 Coach
The credit valuation adjustment (CVA) of a netting set is the market value of the loss from the counterparty’s default: the value of the trades without counterparty risk minus their value with it. With the counterparty’s default time , recovery and discounted exposure,
where and the approximation assumes the exposure and the default independent.
Exemples
Example 18.2 (The netting set’s CVA)
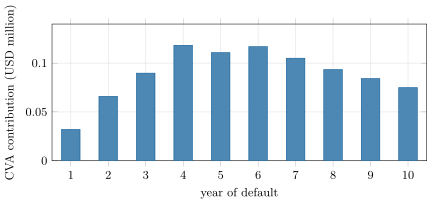
The counterparty of chapter 17’s netting set is quoted at 80, 95, 110, 140, 160 and 175 basis points at one to ten years (illustrative BBB), recovery 40%: its ten-year probability of default is 26.4%. With the exposures discounted path by path along the Hull–White scenarios, the netting set’s CVA is USD 891 342. Standalone, the swap’s CVA is 288 250 and the cross-currency swap’s 768 334: netting saves 16%. Over the ten-year default swap’s risky annuity of 7.45, the CVA is 12.0 basis points a year on USD 100 million (Figure 18.1).