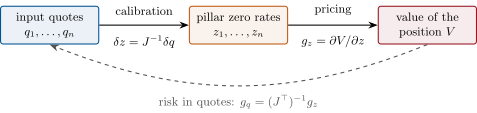
The curve Jacobian is the matrix of the derivatives of the model quotes of the input instruments with respect to the curve’s pillar parameters, at the calibrated curve; its inverse gives how the pillars move when the quotes move, .
 Coach
लॉग इन
पढ़ना शुरू करें
Quantitative Finance · शब्दावली
The curve Jacobian is the matrix of the derivatives of the model quotes of the input instruments with respect to the curve’s pillar parameters, at the calibrated curve; its inverse gives how the pillars move when the quotes move, .