
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Day-one P&L؟

يُعرف أيضًا باسم: day-one P\&L

Definition 27.8 Derivatives and Volatility · الفصل 27 — Managing an Exotic Book

The day-one P&L of a trade is the difference, at inception, between its transaction price and its fair value; under IFRS 9 it is recognised at once only if the fair value is evidenced by a Level 1 price or by a valuation using only observable data, and is otherwise deferred and recognised later only as a factor that market participants would price, including time, changes.
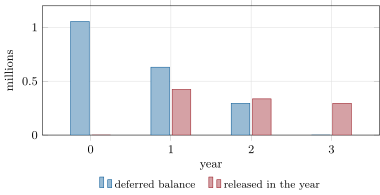
The deferred part of the note’s day-one margin: 1.054 million held back at inception, released as the correlation becomes observable and the note shortens (indices assumed at 95% at each anniversary). Data: the tutorial.
Figure 27.4. The deferred part of the note’s day-one margin: 1.054 million held back at inception, released as the correlation becomes observable and the note shortens (indices assumed at 95% at each anniversary). Data: the tutorial.

أمثلة

Example 27.9 (The deferred profit)

Per 100 million of notes sold at par: margin 2.000 million; bid–offer reserve 0.621; deferred 1.054 (model 0.621, correlation 0.433); recognised at inception 0.325. After one year, with both indices at 95% and the note alive, the correlation trades within 0.47–0.53 and the note has two years left. The correlation reserve falls to 0.071 and the model reserve to 0.559: 0.424 million is released, 0.362 of it from the correlation. After two years, with the indices still at 95%, another 0.336 comes back, and the last 0.295 at maturity (Figure 27.4).

اقرأ في الفصل →