 Coach
The day-one P&L of a trade is the difference, at inception, between its transaction price and its fair value; under IFRS 9 it is recognised at once only if the fair value is evidenced by a Level 1 price or by a valuation using only observable data, and is otherwise deferred and recognised later only as a factor that market participants would price, including time, changes.
उदाहरण
Example 27.9 (The deferred profit)
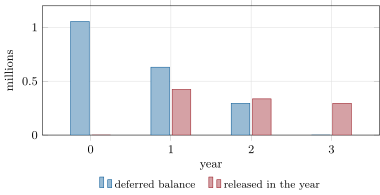
Per 100 million of notes sold at par: margin 2.000 million; bid–offer reserve 0.621; deferred 1.054 (model 0.621, correlation 0.433); recognised at inception 0.325. After one year, with both indices at 95% and the note alive, the correlation trades within 0.47–0.53 and the note has two years left. The correlation reserve falls to 0.071 and the model reserve to 0.559: 0.424 million is released, 0.362 of it from the correlation. After two years, with the indices still at 95%, another 0.336 comes back, and the last 0.295 at maturity (Figure 27.4).