
Semua buku

Profesional

Aplikasi Tentang Pelatih Masuk Mulai membaca

Quantitative Finance · Glosarium

Apa itu Dealer gamma?

Definition 26.4 Markets I: The Ecosystem and Exchange-Traded Markets · Bab 26 — Zero-Day Options, Weeklies and Retail Options Flow

Dealer gamma is the aggregate gamma of the positions held by options market makers, who hedge, as opposed to their customers, most of whom do not. When dealers are long gamma their hedging sells rises and buys falls and tends to damp moves in the underlying; when they are short gamma it buys rises and sells falls and tends to amplify them.
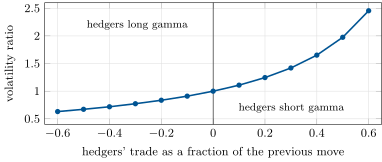
A toy market in which each five-minute return is news plus a fraction of the previous return contributed by hedgers’ trades; the vertical axis is realised volatility over the volatility of the news alone. Feedback of -0.3 removes a quarter of the day’s volatility; +0.3 adds 40%. The effect is asymmetric: amplification compounds. Data: the tutorial’s simulation.
Figure 26.4. A toy market in which each five-minute return is news plus a fraction of the previous return contributed by hedgers’ trades; the vertical axis is realised volatility over the volatility of the news alone. Feedback of −0.3-0.3 removes a quarter of the day’s volatility; +0.3+0.3 adds 40%. The effect is asymmetric: amplification compounds. Data: the tutorial’s simulation.
Baca dalam konteks →