
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Deep hedging؟

Definition 19.2 Machine Learning for Markets · الفصل 19 — Deep Hedging and Machine Learning in Pricing

Deep hedging represents the hedging strategy by a neural network that maps what is observable at each date (time, prices, current holdings) to the new holdings, and trains it on simulated paths to minimise a convex risk measure of the hedged P&L after all frictions (Buehler, Gonon, Teichmann and Wood, 2019).
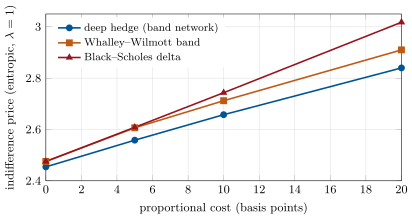
The seller’s indifference price of the one-month at-the-money call (its Heston value is 2.25) under each hedging policy, against the cost of trading the underlying. Data: ml_hedge.hedging.
Figure 19.1. The seller’s indifference price of the one-month at-the-money call (its Heston value is 2.25) under each hedging policy, against the cost of trading the underlying. Data: ml_hedge.hedging.
policyentropic riskexpected shortfall 95%mean coststandard deviation
deep hedge, entropic2.6583.8172.4420.643
deep hedge, expected shortfall2.6713.7632.4570.657
Whalley–Wilmott band2.7124.0442.4240.703
Black–Scholes delta2.7434.0902.5070.595
no hedge8.7679.9922.2352.945
Table 19.1. Selling the call and hedging daily at 10 basis points of cost, on 20 000 test paths: risk measures of the P&L before the premium, its mean loss and standard deviation. Data: ml_hedge.hedging, shortfall_hedge.
اقرأ في الفصل →