
All books

Professional

Apps About Coach Log in Start reading

Quantitative Finance · Glossary

What is Delay cost, opportunity cost, VWAP slippage?

Also known as: delay cost · opportunity cost · VWAP slippage

Definition 23.4 Research Craft: Predictors, Backtests, Measurement, Portfolios · Chapter 23 — Measuring Market Making and Execution

For a parent order decided at price PdP_d, released at the arrival price PaP_a, filled for QQ of its target XX at average price Pˉ\bar P, with the price PeP_e at its end: the delay cost is sQ(Pa−Pd)sQ(P_a - P_d), the execution cost sQ(Pˉ−Pa)sQ(\bar P - P_a), the opportunity cost s(X−Q)(Pe−Pd)s(X - Q)(P_e - P_d); with fees they add up to the implementation shortfall (chapter 19). The VWAP slippage is s(Pˉ−VWAP)s(\bar P - \mathrm{VWAP}), the average price against the market’s volume-weighted average price over the order’s life.
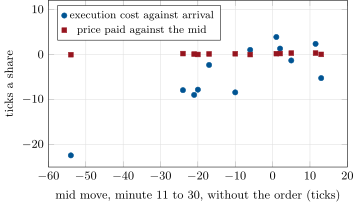
Twelve parent orders: the execution cost measured against the arrival price follows the market’s own move over the order’s life (measured in the same session run without the order); the price paid against the mid at each fill does not. Data: rs_markout.tca_all.
Figure 23.3. Twelve parent orders: the execution cost measured against the arrival price follows the market’s own move over the order’s life (measured in the same session run without the order); the price paid against the mid at each fill does not. Data: rs_markout.tca_all.
Read in context →