
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Delta hedging and gamma؟

يُعرف أيضًا باسم: delta · delta hedging · gamma

Definition 26.2 Markets I: The Ecosystem and Exchange-Traded Markets · الفصل 26 — Zero-Day Options, Weeklies and Retail Options Flow

The delta of an option is the change of its value per unit change of the underlying; delta hedging is holding the opposite quantity of the underlying so that the combined position is insensitive to small moves. Gamma is the change of delta per unit change of the underlying: the rate at which the hedge must be adjusted. A position that is long options is long gamma: its hedger sells as the price rises and buys as it falls. A short-option position’s hedger does the opposite.
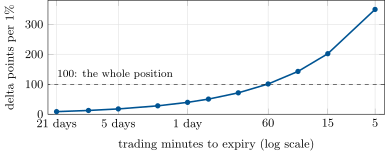
At-the-money gamma at 16% volatility, as the change of delta, in delta points, that a linear extrapolation gives for a 1% move. It passes 100, the whole position, with about an hour to go: from then on a 1% move is more than the option’s entire remaining uncertainty. Data: the chapter’s build.
Figure 26.2. At-the-money gamma at 16% volatility, as the change of delta, in delta points, that a linear extrapolation gives for a 1% move. It passes 100, the whole position, with about an hour to go: from then on a 1% move is more than the option’s entire remaining uncertainty. Data: the chapter’s build.
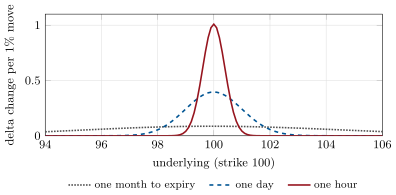
Gamma of a 100-strike option at 16% volatility, expressed as the change of delta for a 1% move of the underlying (linear extrapolation: a delta cannot change by more than one). With a month to go the hedge changes by 0.09 per 1%, whatever the price; with an hour to go, by the whole position if the price is at the strike and by nothing if it is 1% away. Data: the chapter’s build.
Figure 26.3. Gamma of a 100-strike option at 16% volatility, expressed as the change of delta for a 1% move of the underlying (linear extrapolation: a delta cannot change by more than one). With a month to go the hedge changes by 0.09 per 1%, whatever the price; with an hour to go, by the whole position if the price is at the strike and by nothing if it is 1% away. Data: the chapter’s build.
اقرأ في الفصل →