Coach
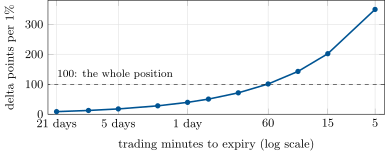
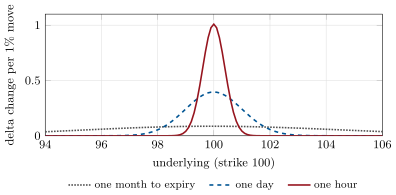
The delta of an option is the change of its value per unit change of the underlying; delta hedging is holding the opposite quantity of the underlying so that the combined position is insensitive to small moves. Gamma is the change of delta per unit change of the underlying: the rate at which the hedge must be adjusted. A position that is long options is long gamma: its hedger sells as the price rises and buys as it falls. A short-option position’s hedger does the opposite.