
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Dividend play؟

Definition 26.5 Derivatives and Volatility · الفصل 26 — Options Market Making in Practice

A dividend play is a trade on the eve of an ex-dividend date in which market makers buy and sell large, offsetting quantities of a deep in-the-money call among themselves and exercise all their long calls; because assignment falls pro rata on all short positions, their short calls absorb most of the non-assignment left by holders who fail to exercise, and each unassigned short call earns the dividend less the time value.
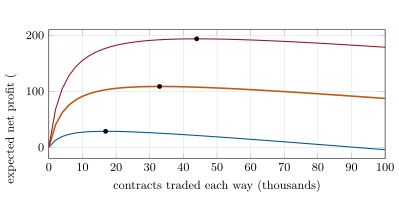
Expected net profit of a dividend play on one call series (10 000 public contracts, $48 gain per unassigned call, $0.50 of fees per contract traded each way) against the size of the trade, for three shares of holders failing to exercise; dots mark the best size. Data: the tutorial.
Figure 26.3. Expected net profit of a dividend play on one call series (10 000 public contracts, $48 gain per unassigned call, $0.50 of fees per contract traded each way) against the size of the trade, for three shares of holders failing to exercise; dots mark the best size. Data: the tutorial.

أمثلة

Example 26.6 (One call series)

A dividend of 50 cents ($50 a contract), a put worth 2 cents ($2), so a gain of $48 per unassigned contract; 10 000 public contracts; fees (an assumption) of $0.10 a contract per trade and $0.05 per exercise, so $0.50 per qq for four trades and two exercises. If 30% of holders fail to exercise, the best trade is 32 947 contracts. It leaves 2 605 short calls unassigned, 87% of the 3 000 that were not exercised, for a gross gain of $125 026, fees of $16 474 and a net of $108 553. With 10% failing the best trade is 16 909 contracts and nets $28 591; with 50%, 43 990 contracts and $193 510 (Figure 26.3).

اقرأ في الفصل →