Todos os livros

Profissional

Apps Sobre Coach Entrar Começar a ler

Quantitative Finance · Glossário

O que é Drift detector, Page–Hinkley test, adaptive windowing?

Também chamado de: drift detector · Page--Hinkley test · adaptive windowing

Definition 12.4 Machine Learning for Markets · Capítulo 12 — Online Learning and Drift

A drift detector watches a statistic of a model in production (its errors, its gains, a feature’s distribution) and raises an alarm when the statistic’s distribution appears to have changed. The Page–Hinkley test accumulates the deviations of the monitored value below its running mean, less a tolerance δ\delta, and alarms when the sum rises more than hh above its running minimum (Page, 1954; Hinkley, 1971). Adaptive windowing (ADWIN) keeps a window of recent values and drops its older part whenever some split of the window into two sub-windows has means further apart than a Hoeffding-type bound at confidence δ\delta (Bifet and Gavaldà, 2007).

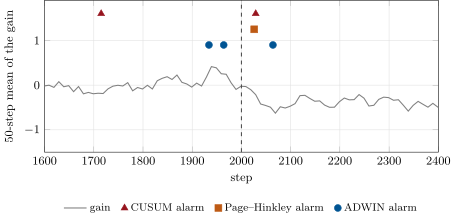
One stream whose coefficients reverse at step 2 000 (dashed): the 50-step mean of the deployed model’s standardised gain, and each detector’s alarms from 300 steps before the reversal to its first alarm after it (markers at arbitrary heights, one row per detector). Data: ml_online.
Figure 12.2. One stream whose coefficients reverse at step 2 000 (dashed): the 50-step mean of the deployed model’s standardised gain, and each detector’s alarms from 300 steps before the reversal to its first alarm after it (markers at arbitrary heights, one row per detector). Data: ml_online.
Ler no capítulo →