 Coach
With flows at times (in periods) and , the Macaulay duration is the present-value weighted average time of the flows, , in years. The modified duration is . The DV01 is the fall in price for a one-basis-point rise in yield, per 100, usually quoted per million of face. The convexity is .
Ejemplos
Example 3.10 (The ten-year note)
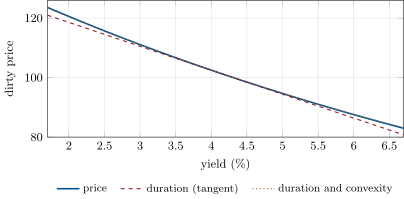
At 4.200% the note of Example 3.4 has a clean price of 100.397405 (100-12+), a dirty price of 100.870911, a Macaulay duration of 8.142 years, a modified duration of 7.975, a DV01 of USD 804 per million and a convexity of 75.8. A 100-basis-point rise costs 7.675 points; duration alone predicts 8.044, duration and convexity together 7.662 (Figure 3.2).