 Coach
A duration-neutral butterfly buys (or sells) a bond in the middle of the curve and sells (or buys) bonds on either side of it, in amounts whose DV01s (Book 2, chapter 3) sum to zero and are split between the wings so that the position is also neutral to a change in slope; it bets on the curvature at the middle.
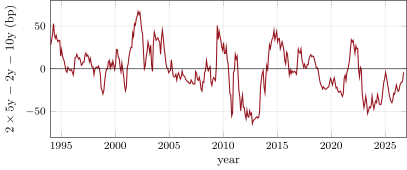
s2_fetch_ust.