
Todos los libros

Profesional

Apps Acerca de Coach Iniciar sesión Empezar a leer

Quantitative Finance · Glosario

¿Qué es Duration-neutral butterfly?

Definition 10.2 Strategies II: Volatility, Relative Value, Macro and the Bank Desks · Capítulo 10 — Government-Bond Relative Value

A duration-neutral butterfly buys (or sells) a bond in the middle of the curve and sells (or buys) bonds on either side of it, in amounts whose DV01s (Book 2, chapter 3) sum to zero and are split between the wings so that the position is also neutral to a change in slope; it bets on the curvature at the middle.
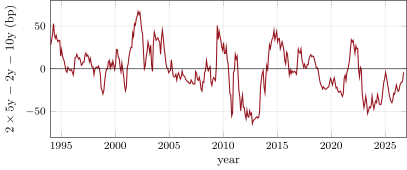
The 2–5–10 Treasury butterfly in yields, monthly means of daily values, January 1994 to September 2026, from the Board’s constant-maturity yields. Derived from the H.15 series on FRED. Data: s2_fetch_ust.
Figure 10.1. The 2–5–10 Treasury butterfly in yields, monthly means of daily values, January 1994 to September 2026, from the Board’s constant-maturity yields. Derived from the H.15 series on FRED. Data: s2_fetch_ust.
Leer en el capítulo →