جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Euler allocation؟

Definition 20.4 Rates, Credit, XVA and Risk · الفصل 20 — The Valuation-Adjustment Desk

Euler allocation assigns to trade ii the contribution ai=ddϵXVA(…,(1+ϵ)Vi,…)∣ϵ=0a_i = \frac{d}{d\epsilon}\mathrm{XVA}(\ldots,(1+\epsilon)V_i,\ldots)|_{\epsilon=0}. When the adjustment is homogeneous of degree one in the trades’ sizes, as CVA is, Euler’s theorem makes the contributions add up to the total; for CVA, ai=(1−R)∑kE[D(0,tk)Vi(tk)1V(tk)>0] ΔPDka_i = (1-R)\sum_k\E[D(0,t_k)V_i(t_k)\mathbf 1_{V(t_k)>0}]\,\Delta\mathrm{PD}_k.

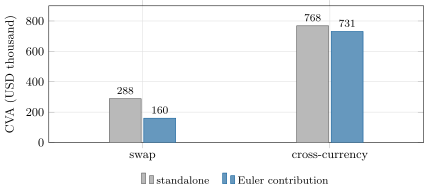
Standalone CVA of each trade against its Euler contribution to the netting set’s CVA. The contributions add up to the set’s CVA; the difference from the standalone figures is the netting benefit, shared in proportion to each trade’s role in the exposure. Data: the chapter’s tutorial.
Figure 20.2. Standalone CVA of each trade against its Euler contribution to the netting set’s CVA. The contributions add up to the set’s CVA; the difference from the standalone figures is the netting benefit, shared in proportion to each trade’s role in the exposure. Data: the chapter’s tutorial.

أمثلة

Example 20.5 (Allocating the netting set)

Of the set’s USD 891 342 of CVA, Euler allocation assigns 160 167 to the swap and 731 175 to the cross-currency swap, against standalone CVAs of 288 250 and 768 334 (Figure 20.2). The swap, which offsets part of the cross-currency exposure, receives most of the netting benefit.

اقرأ في الفصل →