Semua buku

Profesional

Aplikasi Tentang Pelatih Masuk Mulai membaca

Quantitative Finance · Glosarium

Apa itu Euler allocation?

Definition 20.4 Rates, Credit, XVA and Risk · Bab 20 — The Valuation-Adjustment Desk

Euler allocation assigns to trade ii the contribution ai=ddϵXVA(…,(1+ϵ)Vi,…)∣ϵ=0a_i = \frac{d}{d\epsilon}\mathrm{XVA}(\ldots,(1+\epsilon)V_i,\ldots)|_{\epsilon=0}. When the adjustment is homogeneous of degree one in the trades’ sizes, as CVA is, Euler’s theorem makes the contributions add up to the total; for CVA, ai=(1−R)∑kE[D(0,tk)Vi(tk)1V(tk)>0] ΔPDka_i = (1-R)\sum_k\E[D(0,t_k)V_i(t_k)\mathbf 1_{V(t_k)>0}]\,\Delta\mathrm{PD}_k.

Standalone CVA of each trade against its Euler contribution to the netting set’s CVA. The contributions add up to the set’s CVA; the difference from the standalone figures is the netting benefit, shared in proportion to each trade’s role in the exposure. Data: the chapter’s tutorial.
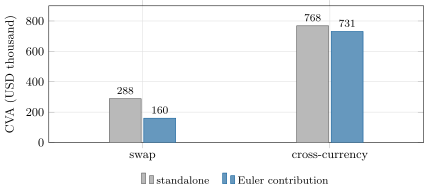
Figure 20.2. Standalone CVA of each trade against its Euler contribution to the netting set’s CVA. The contributions add up to the set’s CVA; the difference from the standalone figures is the netting benefit, shared in proportion to each trade’s role in the exposure. Data: the chapter’s tutorial.

Contoh

Example 20.5 (Allocating the netting set)

Of the set’s USD 891 342 of CVA, Euler allocation assigns 160 167 to the swap and 731 175 to the cross-currency swap, against standalone CVAs of 288 250 and 768 334 (Figure 20.2). The swap, which offsets part of the cross-currency exposure, receives most of the netting benefit.

Baca dalam konteks →