
Tous les livres

Professionnel

Applis À propos Coach Connexion Commencer la lecture

Quantitative Finance · Glossaire

Qu'est-ce que « Exceedance correlation, correlation asymmetry » ?

Aussi appelé : exceedance correlation · correlation asymmetry

Definition 5.6 Research Craft: Predictors, Backtests, Measurement, Portfolios · Chapitre 5 — Stylised Facts of Returns

An exceedance correlation is a correlation between returns measured only on the days when a conditioning variable (a market return, or the two returns themselves) lies beyond a threshold. Correlation asymmetry is the finding that exceedance correlations in falling markets exceed those in rising markets at the same threshold.
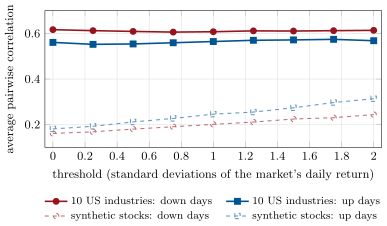
Average pairwise correlation on days when the market fell (down) or rose (up) by more than the threshold. The ten US industry portfolios, 1926–2026, are more correlated on down days at every threshold (0.61 against 0.56 at one standard deviation). The book’s synthetic stocks show the opposite ordering: the simulator misses this fact. Data: Kenneth R. French data library (derived statistics); firm.synthmkt, seed 1.
Figure 5.4. Average pairwise correlation on days when the market fell (down) or rose (up) by more than the threshold. The ten US industry portfolios, 1926–2026, are more correlated on down days at every threshold (0.61 against 0.56 at one standard deviation). The book’s synthetic stocks show the opposite ordering: the simulator misses this fact. Data: Kenneth R. French data library (derived statistics); firm.synthmkt, seed 1.
Lire dans le chapitre →