Coach
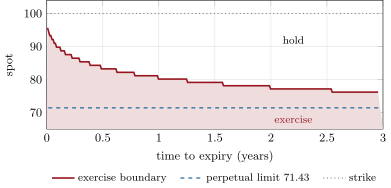
The exercise boundary of an American option is the curve that separates the spots where exercising is optimal from those where holding is: for a put, exercise is optimal when . On the boundary the option equals its exercise value and, in the Black–Scholes model, meets it with the same slope (smooth pasting, One Quant Book 4, chapter 10).