
सभी किताबें

पेशेवर

ऐप्स परिचय Coach लॉग इन पढ़ना शुरू करें

Quantitative Finance · शब्दावली

Exercise boundary क्या है?

Definition 6.3 Derivatives and Volatility · अध्याय 6 — American Options and Early Exercise

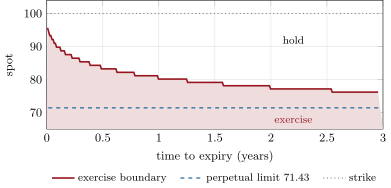
The exercise boundary of an American option is the curve t↦S∗(t)t\mapsto S^*(t) that separates the spots where exercising is optimal from those where holding is: for a put, exercise is optimal when St≤S∗(t)S_t\le S^*(t). On the boundary the option equals its exercise value and, in the Black–Scholes model, meets it with the same slope (smooth pasting, One Quant Book 4, chapter 10).
Exercise boundary of an American put (strike 100, r=5\%, =20\%) by time to expiry, from a 3 000-step tree: below the curve the holder exercises. The boundary rises to the strike as expiry approaches and falls towards the perpetual put’s 71.43 as the horizon lengthens. The steps are the tree’s grid. Data: the tutorial.
Figure 6.2. Exercise boundary of an American put (strike 100, r=5%r=5\%, σ=20%\sigma=20\%) by time to expiry, from a 3 000-step tree: below the curve the holder exercises. The boundary rises to the strike as expiry approaches and falls towards the perpetual put’s 71.43 as the horizon lengthens. The steps are the tree’s grid. Data: the tutorial.
अध्याय में पढ़ें →