Coach
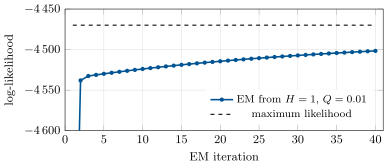
The expectation–maximisation algorithm (Dempster, Laird and Rubin, 1977) maximises a likelihood with unobserved variables by alternating an E-step, the expected complete-data log-likelihood given the data and the current parameters, and an M-step that maximises it. For state-space models the E-step is the smoother and the M-step for and has a closed form (Shumway and Stoffer, 1982).