 Coach
A first-passage model defaults the firm the first time its assets touch a default barrier below the current value, whenever that happens, instead of only at the debt’s maturity. A barrier stands for covenants that let creditors take over, or for the level at which the firm can no longer refinance. The CreditGrades model (2002), published by RiskMetrics with three dealers, puts the barrier at the average recovery on debt times the debt per share and makes that recovery lognormally uncertain, so that default can come as a surprise and short spreads are not zero.
Voorbeelden
Example 14.9 (The firm under a barrier)
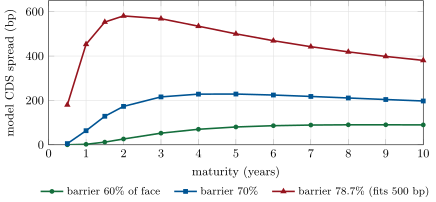
With the barrier at 70% of the debt face, the firm’s model default-swap spreads are 64, 173, 216, 229 and 197 basis points at one, two, three, five and ten years (Figure 14.3); its five-year survival probability is 82.3%. A market quote of 500 basis points at five years needs a barrier at 78.7% of the face.